The Next Era of UGC Platforms
Who will build the next YouTube or Roblox?
November 2026
In 2022 I spent time working for a gaming startup called Manticore Games. They raised $150 million and at the time, planned to build a UGC gaming platform - essentially a Roblox for older kids and adults.
I learned two lessons at Manticore.
Lesson #1: A UGC platform is the holy grail business model in entertainment. A UGC platform only pays creators when their content performs. Meanwhile, a studio has to bet on content before it performs. That’s the difference between YouTube and Netflix. YouTube pays nothing upfront for content. Netflix spends $18 billion a year producing content, and if the content fails Netflix holds the bag. A UGC platform also has better pricing power than a studio. YouTube pays millions of non-full-time creators for their content. Netflix negotiates against the world’s best content producers. TikTok, Facebook and X are also UGC platforms, and better yet they pay creators close to nothing.
Which brings me to Lesson #2: Succeeding as a UGC entertainment platform is incredibly difficult. There’s a chicken-or-the-egg problem. You need users to consume content, which requires creators to make content, which only happens if you have users. Starting that flywheel is the challenge.
Historically, new UGC platforms have emerged once content creation became easier. In video, YouTube emerged when anyone could shoot a clip on a cheap digital camera and upload it. In social media, Instagram and TikTok emerged when everyone got a smartphone. In gaming, Roblox emerged when the company built tools to make games more easily.
I’m excited because in 2026, I think we’re seeing another revolution in how easy it is to create content. And as a result, we’ll see a new wave of unicorn UGC entertainment platforms emerge.
Talking with founders recently, I’ve heard over and over - there’s been a step change in what the newest models can create these last few months. Here are three spaces I’m watching where creation costs are coming down, users are growing, and new UGC entertainment platforms could emerge.
Category #1: Interactive Storytelling
The first category I’ve been intrigued by is AI interactive storytelling, also called AI roleplay.
You might remember the origins of this category with Character AI. The app let you chat with AI characters, and it was an early consumer AI darling for VCs. The tech was cutting edge and people used it a lot, but the company never turned that usage into a real business. In 2024, Google paid $2.7 billion to license its models and hire its founders, and this October the company filed for bankruptcy.
Since Character, a couple things have changed. Inference costs dropped and consumers grew more familiar with this new AI roleplay entertainment format. Now multiple companies have hit $100 million-plus revenue run rates.
Take Wrtn - they’re a Korean startup that makes three apps: Crack in Korea, Kyarapu in Japan and OOC in the US. On OOC, you pick a story that a creator built and you play as the main character. You type what you say and do, and the AI writes what happens next and draws anime-style art for each scene. Wrtn expects over $145 million in revenue this year, 4x-ing last year. What makes these UGC platforms is that creators write the storylines and get paid when they perform. On Crack, the Korean site, a creator can earn up to $700,000 per story.
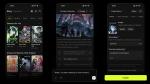
Wrtn isn’t the only one. Chai, the biggest US app, says it passed $100 million in ARR in July with just 15 employees. Zeta, a Korean app, made roughly $50 million in revenue in the first half of the year, and it’s profitable.
Right now a lot of the content on these apps is romantic or NSFW. From talking with founders, I’d estimate it’s at least half. Which is a big reason many Silicon Valley VCs are hesitant to touch this space, and probably why you haven’t heard of it.
I’m interested because I think AI video could take these platforms mainstream. Today these apps are mostly text and images because that’s what is cheap enough to serve. But you can imagine video models getting cheap and good enough that people are watching interactive TV shows made just for them. If I want to go on my own adventure, with a story that’s built around my life, I can. I think that would be incredibly engaging content, and the next entertainment format to help a UGC platform take off.
Category #2: Vibe-Coded Games
The second category I’ve been intrigued by is vibe-coded games.
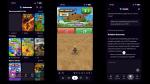
Sekai is a good example. You describe a game in plain English and the AI writes all the code. What comes back is a playable game, which gets published into a feed that works like TikTok. Everyone else scrolls the feed to play, and anyone can remix a game into their own version.
Sekai’s closest competitor is Astrocade. It’s the same idea - a free feed of games that people make by typing a prompt - and it raised $56 million across two rounds, the latest led by Sequoia this spring.
The idea isn’t new. It’s the same vision we were going after at Manticore, and only two companies have really pulled it off. Roblox and Epic Games / Fortnite each have hundreds of millions of players, and both companies are valued north of $20 billion. They’re both great companies. But neither got there the way a startup would want to today. Roblox launched in 2006 and needed more than a decade to break out. Epic built one of the biggest games in the world first, then opened it up to creators. Roblox had a decade, and Epic had Fortnite.
Historically, the challenge has always been creation. That’s what made Lesson #2 so hard at Manticore: if it’s technically hard to make a game, very few people will take the time to teach themselves how. On Roblox it got easier, but it’s still hard for most people. You have to learn Roblox Studio and a programming language called Luau, so the money flows to a small set of experienced studios. Roblox’s top 10 creators averaged $65.7 million in payouts last year, while the median creator made about $1,500. Compare that to YouTube, where all you need to post a video is an iPhone.
What changed is the models. You can now one-shot a game that’s fun to play. Simon Willison, a developer who writes awesome essays about AI, called October the inflection point for vibe-coded games after he built a great spot-the-difference game from one prompt with no follow-ups. Roblox is seeing it too. A few months ago, two games made almost entirely with AI, Break and Steal an Egg and Huss Valley, broke into its top 20 by concurrent players.
The new platforms are finding traction. Astrocade doubled from 5 million to 10 million monthly players in four months. Sekai says people spend more than an hour a day in its app.
What I don’t know yet is how these platforms make money. Interactive storytelling apps charge subscriptions and microdrama apps charge per episode, but vibe-coded games are mostly free today. It could be ads, it could be charging creators to make games, or it could be in-app spending like Roblox, where players buy a currency to spend inside games and the platform takes a cut.
Most of these games are pretty basic right now. Astrocade’s most popular games include plenty of Minecraft clones and knock-offs of hit Roblox games. A lot of what’s in the feeds is fun for about thirty seconds, and I get why people might look at this category today and dismiss it. But if you believe models will continue to improve, it will be possible to one-shot prompt better and better games. Take that far enough, and you can imagine someone prompting a game with the quality of GTA, except it’s set in their own city, their friends are the characters, and the story is about whatever they’re into. I think people would lose hours in a AAA game made just for them.
Category #3: AI Microdramas
The third category I’ve been intrigued by is microdramas. This category’s different from the first two I mentioned. It’s the most mature and mainstream of the three. And most of the market leaders look more like studios (e.g. Netflix) than UGC platforms (e.g. YouTube).
Microdrama apps are basically streaming apps for mini-movies made for your phone. The shows are cut into one- to two-minute vertical episodes. The first few are free, each one ends on a cliffhanger, and then you pay to keep watching. ReelShort is one of the largest players. It’s on track to make $1.05 billion (yes, billion) in revenue this year.
They write, produce and own their shows, and spend heavily on marketing to acquire an audience. More than half of ReelShort’s revenue last year went to marketing, mostly Meta and TikTok ads.
But we’ve seen a drastic change in how these shows get produced. A year ago these shows were shot with real actors on real sets, for $100,000-$300,000 a show. Now the vast majority of new shows across apps are AI-generated, and a show can cost as little as a few thousand dollars in tokens.
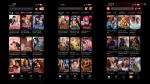
This is exciting for UGC because once a show doesn’t need actors or a crew, the only bottleneck is the creative inspiration. And really any person can become a creator. In March an anonymous TikTok account posted an AI-generated series called Fruit Love Island, a dating show where every contestant is a piece of fruit. It got 300 million views in nine days. It’s incredibly entertaining.
A creator-led model could fix the biggest problem in this microdrama category, which is acquisition. It only gets harder as more copycats launch. Creators bring their own followers with them, and the platform pays them a share of what their shows make instead of paying for ads up front. I wouldn’t be surprised if more microdrama apps lean into creator-led models. One app I find interesting is Inkitt. Anyone can publish a story there, and Inkitt takes the best-performing ones and turns them into microdramas for its own apps, some shot with real actors and some made entirely with AI. So the stories come from creators, even if Inkitt still makes the shows.
The catch is that TikTok may already be the UGC platform for microdramas. Fruit Love Island took off there, and TikTok launched its own microdrama app, PineDrama, in January. Its parent company has done this before. In China, ByteDance’s free microdrama app Hongguo has 430 million monthly users, more than Tencent Video. So I’m less sure a new platform emerges here than in the first two categories.
Who wins?
So by now, it’s clear that new forms of entertainment are emerging with AI. And the creation tools are getting good enough that creator-led models are actually possible. But if anyone can create, creation isn’t what separates the winners anymore.
There are a couple of things that I don’t think will crown the winners. First, I don’t think the winner will have much of a technical moat; I’ve met companies that post-trained their own models, and the next model from Anthropic or OpenAI just ended up being better than theirs. Second, I don’t think platforms will win based on any one piece of viral content. In theory, whenever a content type performs on one platform, someone could just copy it onto their preferred platform.
Instead, there are three questions I’d ask.
1. How does it acquire organic users? Any company can buy users with paid ads. But I don’t think you want to win on paid acquisition alone, because that means raising a lot of expensive venture dollars. You want some kind of viral growth loop, where people see your product out in the world and show up on their own. Pretty much every social media platform had one early on. A lot of YouTube’s early growth came from people embedding videos on MySpace, and TikTok put its watermark on every video so that when clips got reposted to Instagram, they were basically free ads. Honestly I don’t know what the loop looks like for these new categories yet. Maybe it’s content that’s built to get shared on social media, maybe it’s some kind of refer-a-friend mechanic.
2. Are there network effects for users and creators? Does the platform get better as more people join it? What I’d want to see is that as the user and creator bases grow, retention gets stronger. Maybe that’s because users see their friends on the platform and want to play with them (which I think is a big reason kids stay on Roblox). Or maybe it’s that more users bring more creators, since creators want to go wherever the biggest audience is. I’m not sure which one matters more for these categories.
3. How does it work with IP? A lot of these companies are ripping off IP they don’t own. In theory all of that content could get taken down. But we’ve seen this play out before in entertainment. YouTube was full of pirated TV clips in its early days, and Viacom sued it for $1 billion. By then YouTube’s audience was too big to ignore, and today the same media companies post their own clips there. The playbook is to fly under the radar, build the audience, and then cut deals with the IP owners once you have enough leverage that they need you. So IP ends up working like a growth loop, and I’d bet that any winning UGC platform leverages premium IP to grow its audience in the early days. The risk is that you end up as Napster instead, and get shut down before you’re big enough to negotiate.
The obvious pushback is that the incumbents just win. Roblox, Meta and TikTok already have the users, and they’ll latch onto new entertainment mediums. But new formats have usually ended up creating new platforms; for example, YouTube didn’t come from a TV network and TikTok didn’t come from Facebook. I think that’s because incumbents are built around the format that made them big, so a new format tends to end up as a tab inside the old product (think Reels inside Instagram) instead of the whole thing. And people go to an app for one thing. Once a new product becomes the place for that thing, with its own creators and its own culture, it’s really hard to pull people back into an older app that copied the feature. Meta pushed Threads to every Instagram user, and X is still where people go to argue about the news.
I’m excited to see which UGC platforms emerge across these categories. I’d just caveat that the product that becomes a generational company might be outside what any of us can imagine today. Ten years ago, few people would have guessed that the average TikTok user would spend more than an hour and a half a day watching short-form videos on their phone.
If you’re building a UGC platform in any of these categories, please reach out. The Will Ventures team would love to meet you.